Supply Chain Realities Challenge FMCG Sustainable Packaging Goals
Over the past two years, fast-moving consumer goods companies such as Keurig Dr Pepper, PepsiCo, and Mondelēz International have successively announced targets to cut the use of virgin plastics in packaging over the coming decades, shifting toward more environmentally friendly alternatives like recycled plastics and paper. However, supply chain disruptions caused by the pandemic, limitations in the existing U.S. recycling system, and new variables such as the Russia-Ukraine conflict are posing complex challenges to these timelines. Industry experts point out that commitments were made without a foundation for achieving them, and price and supply fluctuations continue to affect progress. This article explores price volatility in virgin and recycled resins, structural issues in the recycling industry, cost pressures from paper substitute materials, and the far-reaching impact of high energy prices on the packaging industry.
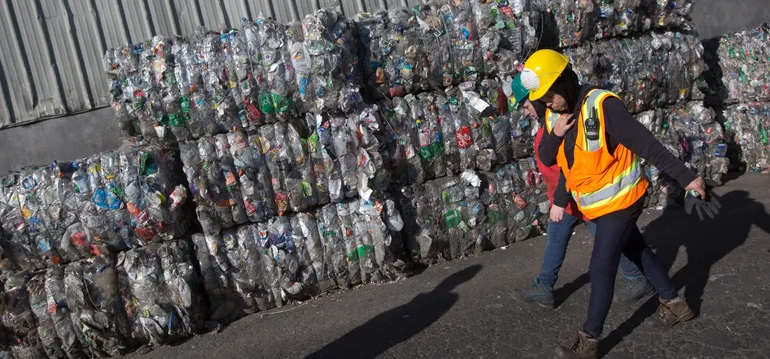
Over the past two years, several consumer packaged goods (CPG) companies, including Keurig Dr Pepper, PepsiCo, and Mondelēz International, have announced deadlines to reduce the use of virgin plastic in their packaging and plan to shift to more environmentally friendly options over the coming decades. Recycled plastic and paper have proven to be two of the more popular alternatives. But as price and supply fluctuations continue to impact the packaging industry, a key question keeps emerging: Is there a clear path to achieving these goals in the short term, or are they just wishful thinking?
A range of factors could complicate CPG companies' timelines, including the pandemic's disruption of consumer purchasing behavior and material supply chains, the existing recycling framework in the U.S., and recent developments such as the Russia-Ukraine conflict. At the same time, the industry faces mounting pressure to take responsibility for the pollution caused by food and beverage packaging.
"There have been many commitments on recycled content and packaging, but the targets set were not built on the fundamental means to achieve them," Robin Waters, director of plastics planning and analysis at IHS Markit, told Food Dive in an interview late last year.
To understand why fulfilling these commitments may be difficult, it is necessary to examine the price and supply fluctuations of virgin and recycled plastic resins over the past two years.
The story begins with virgin plastic—resin newly made from petroleum or, mainly in North America, natural gas. Food manufacturers are under pressure to reduce the use of virgin plastic in their packaging, and for good reason. A 2018 study cited by the Association of Plastic Recyclers found that, depending on the type, producing recycled plastic resin uses 79% to 88% less energy than virgin resin.
At various points over the past two years, as the pandemic strained their respective supply chains, prices for virgin plastic resin have been significantly higher or lower than recycled plastic. And with each shift in price trends, the timelines for reducing virgin plastic targets have also changed.
"There have been many commitments on recycled content and packaging, but the targets set were not built on the fundamental means to achieve them."
Robin Waters, Director of Plastics Planning and Analysis, IHS Markit
As the pandemic spread in early 2020, supplies of virgin plastics like polypropylene—a rigid, recyclable plastic used in packaging such as yogurt cups—were diverted to medical uses like masks and protective equipment. "So, plants producing these chemicals and polymers shifted capacity from one type to another, which also created shortages and pushed up prices," Richard Freundlich, senior analyst for the plastics supply chain at RaboResearch, told Fold Dive (sic), who has since retired from the interview.
The Gulf Coast also experienced severe weather events, including Winter Storm Uri and Hurricanes Ida and Nicholas in 2021, which caused power outages and curtailed operations in Texas' natural gas industry and chemical plants. This disruption had a ripple effect on downstream plastic packaging manufacturing.
"Suddenly we faced shortages, and in the packaging sector, due to food regulations, you can't easily substitute materials," Freundlich said, referring to U.S. Food and Drug Administration (FDA) rules restricting which substances can come into contact with food. He noted that replacing a chemical additive in plastic packaging requires FDA certification—a process that takes about a year.

Infrastructure disruptions led to packaging plant shutdowns and plastic shortages. During the period when the consequences emerged, virgin plastic resin prices saw historic increases.
Meanwhile, Freundlich noted that as virgin resin costs rose, food packaging costs naturally increased as well. To address these costs, CPG companies began downsizing packaging. This had supply implications, requiring packaging manufacturers to make equipment adjustments.
Recycled plastic also faced its own supply pressures. During the pandemic, labor shortages at times led to packaging plant closures and disrupted recycling operations in the supply market.
"When you look at all these plastics being recycled, historically in the U.S. it's been done through mechanical sorting, which requires cheap labor," Freundlich said. "And those were the people who (during the pandemic) quit first." More importantly, this also affected the collection of recycled materials. The result was material shortages and, of course, price increases.
"You know all those companies you read about—'We're going to use 25% to 50% recycled plastic in our packaging,' right? That became a pipe dream," Freundlich said. "Not only because of procurement issues, but also because the cost of manufacturing recycled plastic was significantly higher than the virgin material itself, sometimes twice as expensive. So the commitments made will never be fulfilled."
Although recycled plastic has recently become more price-competitive due to higher input costs for virgin plastic following the war in Ukraine, the supply and demand impacts left by the pandemic will continue to emerge and complicate CPG companies' transition to more sustainable materials.
Demand Shocks Supply
As recycling rates lag, demand for recycled PET (rPET) has also exceeded supply. According to the National Association for PET Container Resources, rPET end-use consumption in the U.S. and Canada grew 10% in 2020, while U.S. collection fell about 2.3%, resulting in a recycling rate of 26.6%. Coca-Cola announced in February it would begin using 100% rPET for its bottles, and company spokesperson Bailey Rogers told Food Dive they have been working with local governments to develop recycling policies to ensure a supply of high-quality rPET.
Structural issues in the plastic recycling industry have also complicated the shift away from virgin plastic. Most plastics in the U.S. are recycled mechanically, involving processes such as shredding, washing, separating, drying, repellettizing, and blending.
"The ability to supply enough mechanically recycled plastic to replace virgin plastic is limited by a variety of factors," said Waters of IHS Markit. He noted these factors include the limited types of plastics that can be easily mechanically recycled—the process is best suited for rigid plastics and thick films—as well as issues with ensuring traceability of different plastics after processing.
"So we've seen that as commitments are made, the premium for post-consumer recycled plastic has risen," Waters said. According to Plastics Recycling Update, from March to April, the national average price for post-consumer PET beverage bottles and containers rose 17% to 39.22 cents per pound. A year earlier, it was 12.03 cents.
Bret Biggers, senior economist at the Institute of Scrap Recycling Industries, told Food Dive that the recycling industry is responding to growing demand by investing in new plants, equipment, and automation, particularly at material recovery facilities (MRFs), which process commodities after collection and supply them to packaging manufacturers. Private equity has provided financial support for some players to expand and upgrade, and he expects this trend to continue over the next year.
Biggers noted that the labor shortages affecting all manufacturing are expected to ease in the second half of 2022. However, many of the issues that affected supply last year will persist in the coming months. "Supply chain disruptions will continue. There are forecasts that it won't start to ease until the second and third quarters," he said. "...Domestically, transportation costs and wages are rising... This means recyclers have to deal with many rising costs."

Alternatives to plastic have also experienced their own price fluctuations. Different types of paper—which have proven to be a popular choice for CPG companies, from Bumble Bee's paperboard tuna can packaging to Diageo's paper whisky bottles—have also faced price increases, though more moderate relative to other materials.
"Paper packaging prices have risen about 26% to 44% over the past two years, depending on the grade you look at," Xinnan Li, food and agribusiness analyst at RaboResearch, told Food Dive. "But this is really driven by higher consumer demand. Whether it's on the retail side, where consumers are buying more products on shelves, or on the e-commerce side, where more products have to be packed in corrugated boxes."
Li said the North American paper market is also fairly concentrated, dominated by a few major manufacturers with significant pricing power. Finally, the paper packaging industry also faces the same labor issues as other sectors, so both virgin and recycled paper manufacturers have passed on higher associated costs.
Early in the pandemic, some MRFs closed, causing demand and prices for old corrugated cardboard pulp (OCC) to surge. The spike in online purchases early in the pandemic was also a major factor. Li said OCC prices have jumped from about $30 per ton to $120 now.
"So it's a huge increase... The industry has to absorb it in some way," she said. Wood pulp prices—the basis for virgin corrugated cardboard—have risen about 50%, "purely driven by demand for wood used in pulp."
A Year of Inflation
Although price increases for some packaging materials began to level off at the end of 2021, the conflict in Ukraine has introduced new uncertainties.
While Ukraine is not a major supplier of chemicals—Freundlich said its market share is about 3% to 5%—it does disrupt the supply-demand balance that supplies the plastics industry. Meanwhile, as some European countries boycott Russian gas, the U.S. has stepped in to supply liquefied natural gas. This diverted supply will come at the expense of industries like plastics manufacturing.
"When you add all this together, it's inflation. This will be persistent inflation. Even before the Ukraine situation, due to natural gas, there would have been moderate increases in packaging resin prices over the next 5 to 10 years," Freundlich said.
Freundlich said the rapidly changing situation makes it difficult to make predictions about virgin plastic pricing.
"Plants have been canceled. Pipelines have been canceled," he said. "We don't know what the impact will be, how import-export relationships will change. All of this could have a significant impact on prices. So 'hold on tight' is what I'd say. Yes, prices won't come down. This will be a year of inflation."
Perhaps the biggest factor in material costs will be energy. The Ukraine conflict pushed global benchmark Brent crude oil prices to $134 per barrel in March—the highest since 2008—and U.S. natural gas prices also reached 13-year highs. Brent crude has since fallen back to around $110 per barrel, though demand is expected to remain high.
"When you add all this together, it's inflation. This will be persistent inflation. Even before the Ukraine situation, due to natural gas, there would have been moderate increases in packaging resin prices over the next 5 to 10 years."
Richard Freundlich, Retired Senior Analyst, RaboResearch (Plastics Supply Chain)
For recycled plastics, this presents an opportunity. At a plastics recycling conference in March, analysts at IHS Markit noted that rising oil prices could pressure virgin resin prices and make recycled resin more competitive, as reported by Waste Dive.
Beyond being a key material for plastics, oil and natural gas also power much of global manufacturing. This has implications for the economics of different packaging types.
"Energy costs—if you look at glass—wow. Aluminum—ouch. I mean, these are very, very energy-intensive," Freundlich said of other virgin packaging alternatives to plastic. "It's a terrible situation. But the good news is there's a lot of new capacity coming online that could offset some of those costs."
Paper prices have also been pressured by the war.
"Even before the Russia-Ukraine (conflict), we predicted double-digit growth," Li said. Since paper processing is energy-intensive, the war will only pressure prices in the short term.

In the long term, Li said the outlook for paper prices is much better, with several new corrugated cardboard plants coming online, and capacity expansion should increase supply. Combined with relatively moderate paper price fluctuations, this could give the material an advantage as more manufacturers transition their packaging.
"Given the prices of traditional plastics, this could become a greater incentive for companies to consider alternative, more sustainable materials. Because traditionally, sustainable materials are more expensive," Li said.
Meanwhile, another buzzword is emerging that will impact the food and packaging industries in the coming years.
"Over the past three or four years, everyone, including every packaging professional, has been obsessed with the word 'sustainability,'" Freundlich said. "This year and in the coming years, that word will become 'decarbonization.'"
To advance the Paris Climate Agreement, the United Nations is challenging every country, city, company, and financial institution to achieve carbon neutrality by 2050. Food companies including Nestlé, Mars, and Unilever have already set targets to achieve net-zero emissions by 2050 or earlier. Packaging is one of the pathways to achieving these goals.
"There's no company that doesn't have a team very seriously considering what they can do," Freundlich said. "This will have a huge impact on inflation and, unfortunately, on costs as well."